Industries We Serve
What tax credit compliance requirements apply to solar and energy storage projects?
Clean Energy Compliance
Manage the requirements behind your tax credit.
Solar and energy storage projects face compliance requirements that vary by credit, project type and timeline. Empact combines NexusIQ®, its AI-native platform, with managed compliance services to identify and resolve issues and maintain the supporting record.
Explore NexusIQ- Prevailing Wage & Apprenticeship (PWA)
- FEOC / PFEForeign Entity of Concern / prohibited foreign entity
- Beginning of Construction (BOC)
- Domestic Content
- State Compliance
Requirements depend on the credit, project type and timeline.
Project Type
Choose your project type.
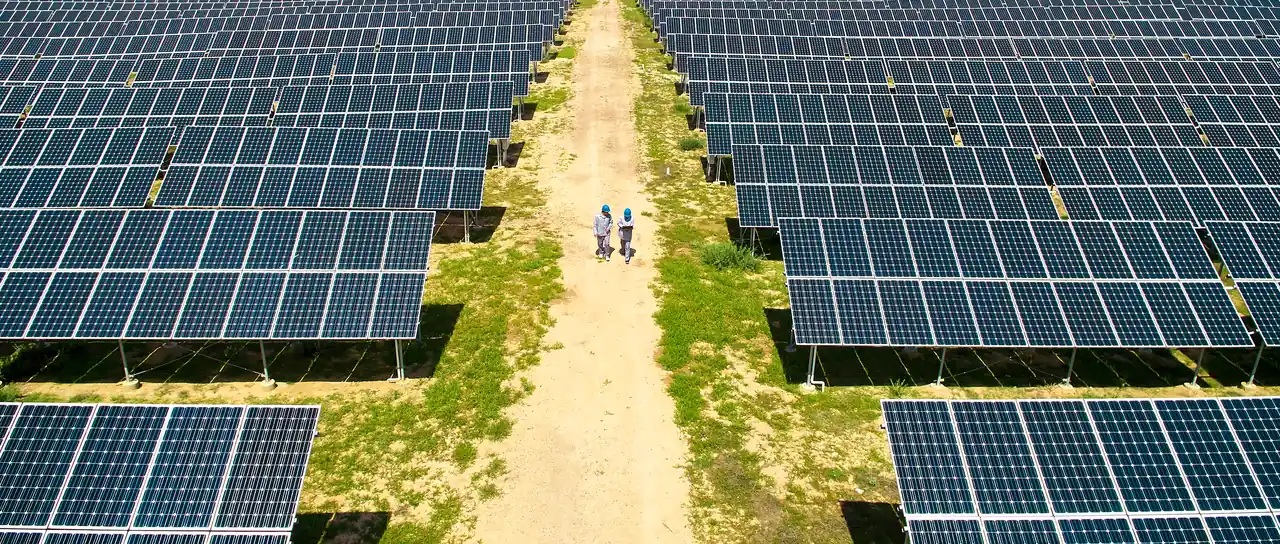
Solar
When construction starts matters most.
- Beginning of Construction
- PWA
- Domestic Content
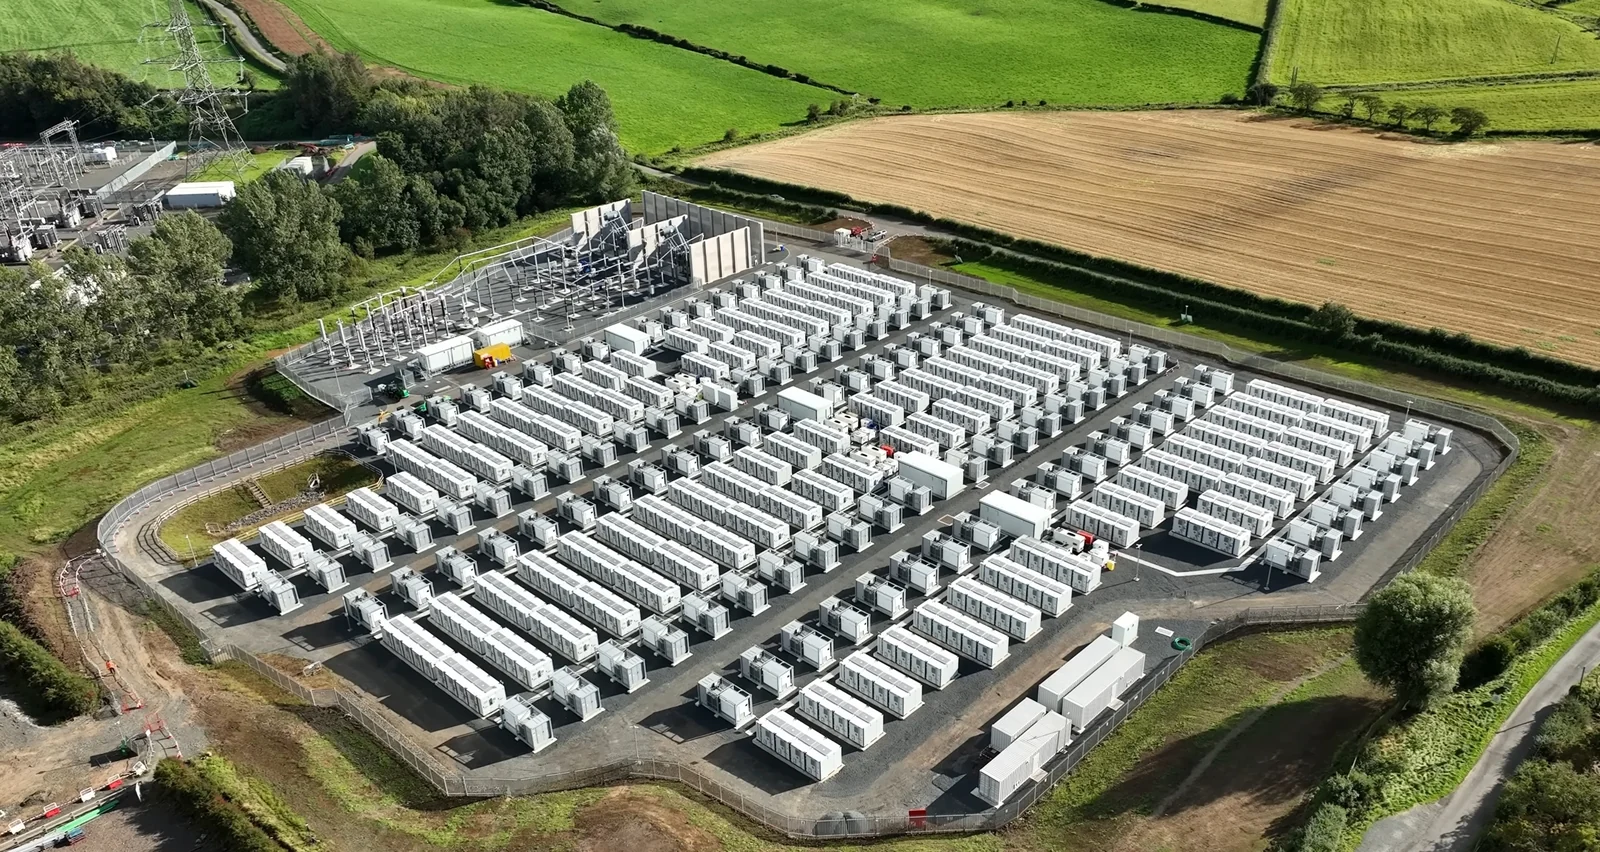
Energy Storage
Where components come from matters most.
- FEOC / PFE
- Domestic Content
- PWA
Building solar plus storage? Both pages apply.
Compliance Record
The claim depends on the underlying records.
A compliance issue may surface at financing or transfer long after the work or sourcing decision behind it. Empact reviews the evidence and works with project teams to resolve identified issues and documentation gaps.
- 01
Underlying records
Payroll, timekeeping, contracts and supplier documentation.
- 02
Review and resolution
NexusIQ reviews the evidence and identifies issues. Empact validates the supporting records and coordinates resolution.
- 03
Compliance record
Findings, actions taken and outstanding items organized for project teams and authorized reviewers.
Credits
Which credits apply
| Credit | What it covers | What Empact manages |
|---|---|---|
| Section 48E, clean electricity investment credit | Investment in qualifying zero-emissions generation and energy storage facilities. | PWA documentation, including prevailing wage records for alteration and repair work during the recapture period; FEOC / PFE compliance, including ongoing review where required; beginning of construction evidence; domestic content documentation where the bonus is pursued. |
| Section 45Y, clean electricity production credit | Electricity produced and sold by qualifying zero-emissions facilities. | PWA documentation, including prevailing wage records for alteration and repair work during the credit period; FEOC / PFE compliance across the applicable tests; beginning of construction evidence; domestic content documentation where the bonus is pursued. |
| Sections 48 and 45, legacy credits | Projects that began construction before 2025 under the former investment and production credits. | PWA documentation, beginning of construction evidence supporting legacy credit eligibility, and domestic content documentation where the bonus is pursued. |
The FEOC / PFE restrictions apply to Sections 45Y and 48E, not to the legacy Section 45 and 48 credits. Tax rules and guidance continue to evolve, and applicable requirements depend on the credit, project type and project timeline.
Empact maintains the compliance record against the requirements applicable to each project.
Our Approach
Why Empact
Highest-Quality Compliance
We review the underlying records, not just the reports.
One Stop Compliance Shop
Every requirement behind your tax credit, one partner.
- PWA
- FEOC / PFE
- Beginning of Construction
- Domestic Content
- State Compliance
Guaranteed Outcomes
Certified compliance, backed by a financial guarantee.
For qualifying fully managed PWA engagements. Compliance certification is within the engagement scope.
Engagement
Engagement options
Choose NexusIQ software, a hybrid engagement or fully managed compliance services based on the contractor coordination, supplier documentation and reporting your project needs.
- Software
- Hybrid
- Fully Managed
Empact will be first on my list to contact if we ever need to procure these types of services for ourselves in the future! Best response time and understanding of the nuts and bolts by far!
FAQ
Frequently Asked Questions
Solar and energy storage projects can face federal and state compliance requirements, including prevailing wage and apprenticeship (PWA), Foreign Entity of Concern (FEOC) / prohibited foreign entity (PFE) requirements, beginning of construction (BOC), domestic content and state labor requirements. Which requirements apply depends on the credit, project type and project timeline. Empact identifies compliance issues as work happens, works with the project team to resolve them and maintains the compliance record throughout the tax credit lifecycle.
Section 45Y is a production-based credit for electricity produced by qualifying zero-emissions facilities. Section 48E is an investment-based credit for qualified investment in qualifying zero-emissions electricity facilities and energy storage technology. The credits generally apply to qualifying facilities or property placed in service after 2024, subject to project-specific requirements and limitations.
Prevailing wage and apprenticeship requirements can determine whether a taxpayer qualifies for the increased amount of certain clean energy tax credits, including Sections 45Y and 48E, unless an applicable exception applies. The requirements include wage, apprenticeship and recordkeeping obligations, and prevailing wage requirements can continue for alteration and repair work after a facility is placed in service.
Federal law restricts certain clean energy credits, including Sections 45Y and 48E, based on prohibited foreign entity (PFE) status, effective control and, for certain projects, material assistance from prohibited foreign entities. Foreign Entity of Concern (FEOC) and PFE are related terms with distinct definitions. The legacy Section 45 and 48 credits are not subject to these restrictions. How the rules apply depends on project timing, ownership and sourcing.
Start early enough to capture evidence as sourcing, contracting and construction decisions occur. Beginning of construction dates can have significant tax consequences, particularly under the current rules for solar projects.
More questions? Visit our FAQ.
Next Step
Know what supports your clean energy tax credit.
Discuss your project's credits, timeline and compliance records with Empact.